Home Loan Offset Accounts Explained: How They Can Help You Save on Interest
When comparing home loans, you'll often come across features that promise to help you save money over the life of your loan. One of the most popular is an offset account.
While an offset account can potentially reduce the amount of interest you pay, it's not the right choice for every borrower. The value you receive depends on factors such as your savings habits, loan balance and the type of home loan you choose.
Before selecting a home loan, it's worth understanding how an offset account works and whether it aligns with your financial goals.
What Is a Home Loan Offset Account?
A home loan offset account is a transaction or savings account that's linked to your mortgage.
Instead of earning interest like a traditional savings account, the money in your offset account reduces the balance used to calculate your home loan interest.
For example:
- Home loan balance: $500,000
- Offset account balance: $40,000
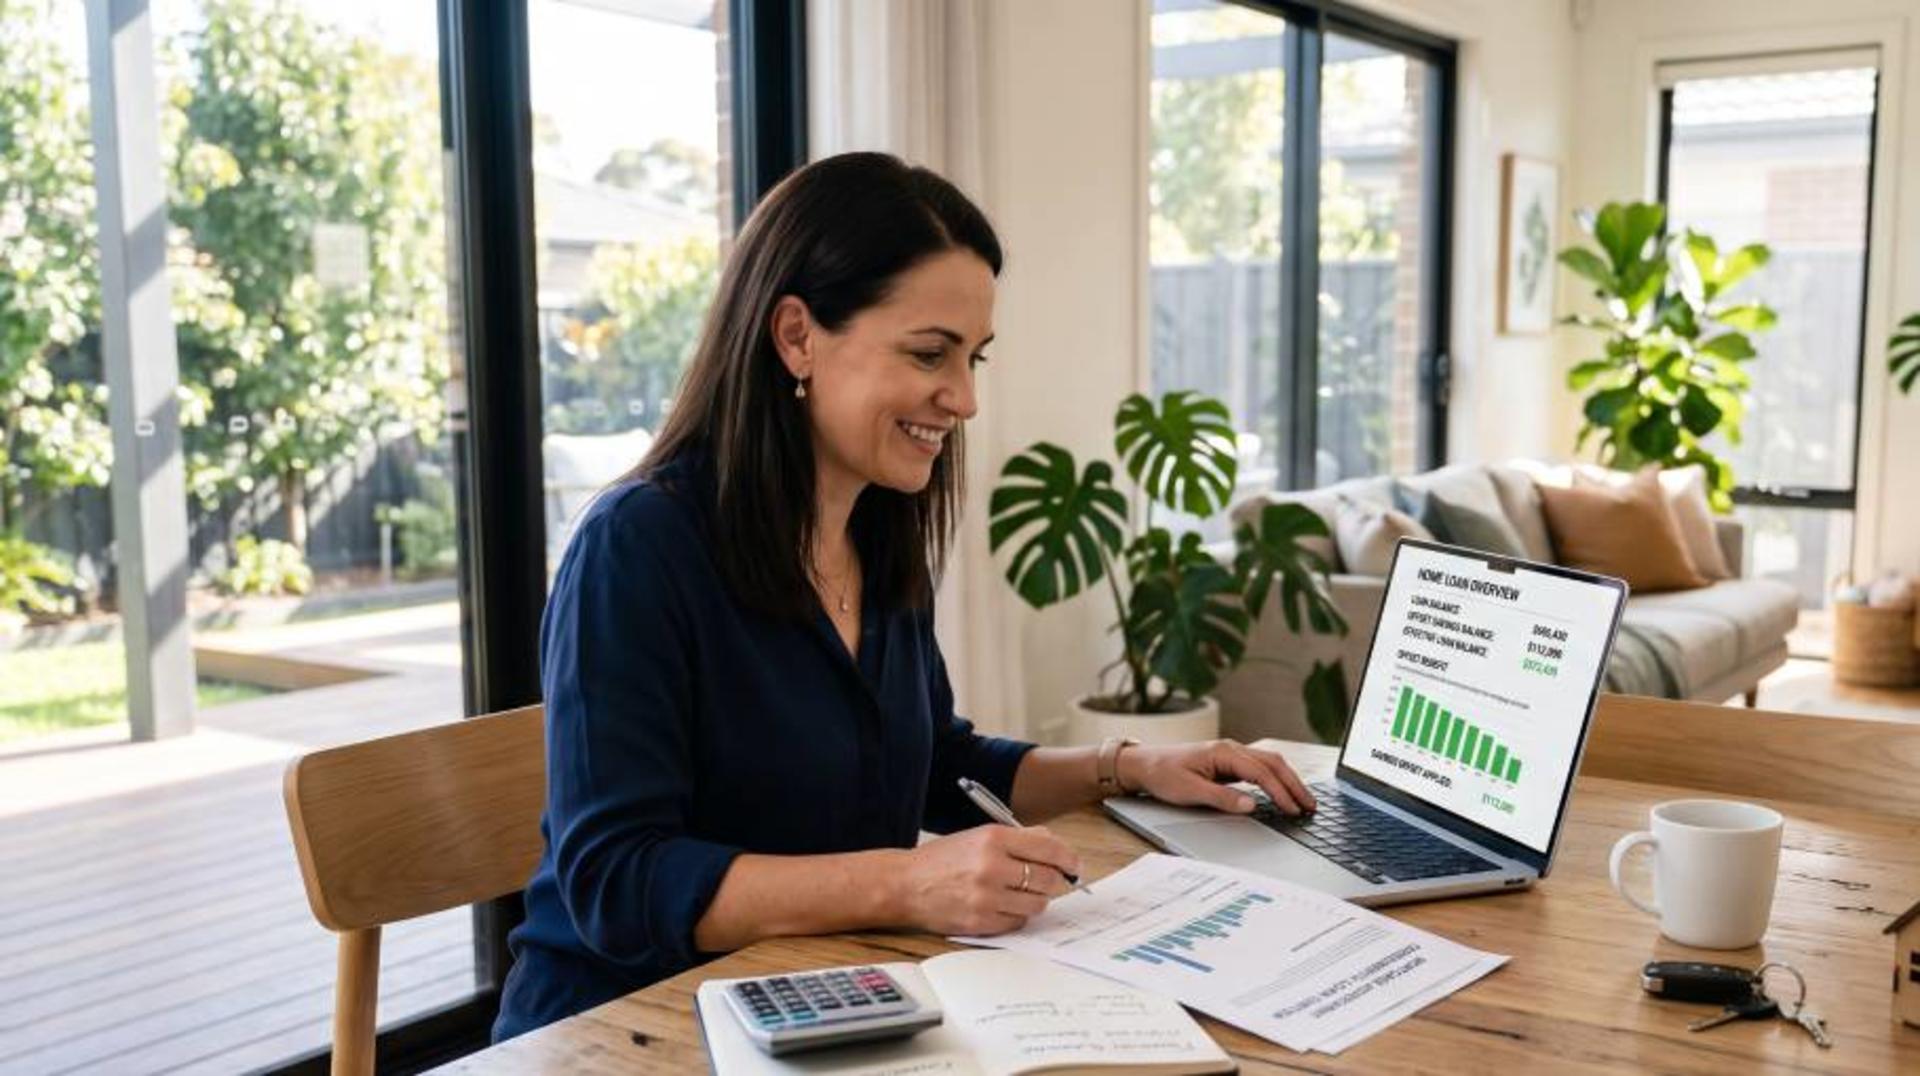
Instead of paying interest on the full $500,000, you'll only be charged interest on $460,000 while that $40,000 remains in your offset account.
This can reduce the amount of interest you pay over the life of your loan and may help you repay your mortgage sooner if your repayments remain the same.
How Does an Offset Account Work?
Every day, your lender compares the balance in your offset account with your outstanding home loan balance.
The funds in the account "offset" part of your loan, reducing the amount on which interest is calculated.
The more money you keep in the offset account, the greater the potential interest savings.
Because it's usually a transaction account, you can generally:
- Deposit your salary
- Pay bills
- Make everyday purchases
- Transfer funds when needed
However, withdrawing money reduces the offset balance, which may increase the amount of interest charged.
What Are the Benefits of an Offset Account?
Many homeowners choose an offset account because it offers flexibility while helping reduce interest costs.
Some of the key benefits include:
Reduce Interest Charges
The primary advantage is paying interest on a smaller loan balance, which can lead to significant savings over time.
Pay Off Your Home Loan Sooner
If you continue making the same repayments while paying less interest, more of each repayment goes towards reducing your loan principal.
Easy Access to Your Money
Unlike making extra repayments directly into some loans, money in an offset account generally remains accessible for everyday use.
"An offset account allows your savings to work harder without locking them away."
Offset Account vs Redraw Facility
Offset accounts and redraw facilities are often confused, but they work differently.
| Offset Account | Redraw Facility |
| A separate account linked to your home loan | Access to extra repayments you've already made on your loan |
| Reduces the balance used to calculate interest | Reduces your loan balance through additional repayments |
| Funds generally remain available for everyday banking | Access rules vary depending on the lender |
| Often available with eligible home loans | Available on selected loan products |
Both features can help reduce interest, but they operate in different ways. Understanding the differences can help you choose a loan that suits your financial habits.
Is an Offset Account Right for Everyone?
Not necessarily. An offset account may be most beneficial if you:
- Maintain regular savings
- Receive your salary into the account
- Keep a healthy account balance throughout the month
- Want flexibility to access your funds
If you rarely keep money in your account, the potential interest savings may be limited.
Some home loans with offset accounts may also have different fees or interest rates, so it's important to compare the overall value of the loan rather than focusing on one feature alone.
Can an Offset Account Save You Money?
Yes, but the amount depends on:
- Your home loan balance
- The amount held in the offset account
- Your interest rate
- How long the funds remain in the account
Even modest savings can reduce the interest charged over many years, particularly on larger home loans.
Using an offset account alongside a realistic repayment strategy may help you become mortgage-free sooner.
If you're still comparing home loan options, our guide on How Does a Home Loan Work in Australia? explains the fundamentals of borrowing for a property.
Should You Choose a Home Loan with an Offset Account?
An offset account can be a valuable feature, but it should be considered alongside other aspects of a home loan, including:
- Interest rate
- Fees
- Loan features
- Repayment flexibility
- Your savings habits
Comparing the overall loan package is often more important than choosing a single feature in isolation. A finance broker can help you compare lenders and determine whether an offset account is likely to provide value based on your financial circumstances.
Conclusion
A home loan offset account can be an effective way to reduce interest costs while keeping your savings accessible. By offsetting part of your loan balance, it has the potential to help you pay less interest and repay your mortgage sooner.
Whether an offset account is the right choice depends on your financial habits and the home loan you choose. Comparing lenders and understanding the full range of loan features can help you make an informed decision.
If you're exploring your home loan options, the team at Pink Loans can help you compare lenders and find a home loan that suits your goals, whether you're looking for an offset account or other valuable loan features.
FAQs
What is a home loan offset account?
A home loan offset account is a bank account linked to your mortgage. The balance in the account reduces the amount of your loan on which interest is calculated, potentially lowering your interest costs.
Is an offset account better than a savings account?
It depends on your circumstances. If your home loan interest rate is higher than the interest you would earn on a savings account, an offset account may provide greater financial benefits.
Can I withdraw money from my offset account?
Yes. Most offset accounts function like everyday transaction accounts, allowing you to access your money when needed. However, withdrawing funds reduces the offset balance and may increase the interest charged on your home loan.
Do all home loans come with an offset account?
No. Offset accounts are available on selected home loan products and may not be offered by every lender. Some loans with offset accounts may also have different fees or interest rates.
Is an offset account worth it?
For borrowers who regularly maintain savings in the account, an offset account can reduce interest costs over time. Whether it's worthwhile depends on your financial habits and the features of the loan.
